

Using a loan broker can be helpful when you want to compare finance options but are unsure where to start. In Australia, a finance broker or loan broker may help personal borrowers, business owners, self-employed applicants and asset finance customers understand which lenders may be worth approaching.
A broker is not the same as a lender. A lender provides the credit. A broker generally acts as an intermediary who gathers information, discusses possible options and may submit an application to one or more lenders on your behalf. The outcome still depends on your circumstances, the information you provide and the lender’s criteria.
What does a loan broker do?
A loan broker helps connect borrowers with lenders or finance products. Depending on the broker’s services and the type of loan, this may include:
- asking about your loan purpose, income, expenses, assets, liabilities and credit history;
- explaining loan types such as unsecured personal loans, secured vehicle finance, business loans or equipment finance;
- identifying lenders from the broker’s lender panel that may consider your scenario;
- helping you understand documents lenders commonly request;
- submitting an application or referral to a lender;
- communicating with the lender during assessment; and
- explaining approval conditions, loan documents and settlement steps if an offer is made.
Some brokers provide broad comparison support, while others specialise in a particular area such as business finance solutions, commercial leasing options, asset finance Australia arrangements or personal loans.
How the loan broker process usually works
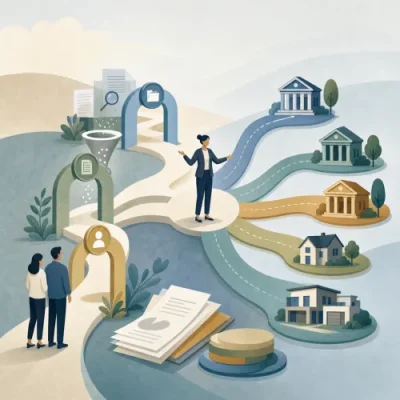
The loan broker process can vary by broker, lender and loan type, but it commonly follows a sequence like this.
1. Initial enquiry or referral
You may contact a broker directly, be referred by a finance website or submit an online enquiry.
At this stage, you may be asked for basic information such as the type of finance you are seeking, the amount you want to borrow, your employment or business status and your preferred contact details.
2. Fact-finding and needs discussion
A broker will usually ask more detailed questions before suggesting possible loan pathways. For a personal loan, this may involve your income, expenses, existing debts, repayment comfort and credit history. For business finance, it may include your trading history, revenue, cash flow, business structure and loan purpose.
This step matters because a broker should not simply send your details to multiple lenders without understanding your situation. A better-prepared application may reduce unnecessary back-and-forth and help target lenders more carefully.
3. Checking possible lender fit
Brokers typically work from a lender panel. This is the group of lenders they are accredited with or able to access. A broker may compare policies, pricing indications, security requirements and assessment criteria across that panel.
A lender panel is not the whole market. One broker may have access to different lenders from another broker. It is reasonable to ask which lenders are on the panel and whether the broker has considered options outside their usual recommendation.
4. Application preparation
If you decide to proceed, the broker may help you prepare documents and complete application details. Business borrowers may find it useful to read about business loan documents and eligibility in Australia before speaking with a broker, as lenders often assess cash flow, financial records and existing liabilities.
If you are seeking finance for cars, utes, machinery or equipment, the broker may also discuss the asset type, invoice or quote, business use, possible security and repayment structure. For more context, see this guide to vehicle and equipment finance for Australian businesses.
5. Lender assessment and conditional approval
Once an application is submitted, the lender assesses the information. This may include credit checks, bank statement review, verification of income or business activity, valuation of secured assets and assessment of repayment capacity.
Any approval may be conditional. Conditions could include providing extra documents, signing guarantees, confirming insurance, paying deposits or accepting specific loan terms. Approval, pricing and available loan structures are not guaranteed.
6. Loan offer, documents and settlement
If the lender offers finance, the broker may explain the next steps and help coordinate loan documents. You should still read all loan documents carefully before accepting. Check interest rates, comparison rates where applicable, fees, repayment frequency, early payout costs, security, default consequences and any broker or lender charges.
Loan referrals: what happens after you submit an enquiry?
Many finance websites and intermediaries use referral pathways. This means your enquiry may be passed to a participating broker, lender or finance intermediary who can contact you to discuss your needs. A referral is not the same as loan approval and does not mean the referred party will be suitable for your circumstances.
Before you provide detailed personal or financial information, ask who you are dealing with, what organisation they represent, how your information will be used and whether they are a broker, lender, credit representative or referral partner. You can also review available broker information to understand how broker support may fit into the finance process.
Broker commissions, fees and disclosure
Loan brokers may be paid in different ways. Common arrangements include:
- Upfront commission: paid by the lender when a loan settles.
- Trail commission: ongoing commission paid by the lender while the loan remains active.
- Broker fee: paid directly by the borrower, sometimes only if finance is approved and accepted.
- Referral fee: paid to a referrer for introducing a borrower to a broker or lender.
Commission does not automatically mean a recommendation is unsuitable, but it can create conflicts that should be disclosed and managed. You can ask the broker:
- how they are paid;
- whether any fee is payable by you;
- whether commission differs between lenders;
- whether they receive volume bonuses or other benefits;
- what happens if you refinance, repay early or do not proceed; and
- whether all fees are included in the written quote or credit proposal.
Do not rely only on a monthly repayment figure. Consider the total cost of borrowing over the full loan term, including fees, interest, establishment costs, ongoing charges and early exit costs where relevant. If you want to estimate affordability before speaking with a broker, the site’s loan calculators may help you model repayments or compare scenarios using your own assumptions.
Understanding lender panels
A lender panel is one of the most important things to understand when using a broker. The panel determines which lenders the broker can usually place loans with. A larger panel may provide more options, but quality of fit matters more than the number of lenders listed.
Ask whether the broker considered multiple lenders and why a particular lender was suggested. The answer should relate to your circumstances, the loan purpose, eligibility criteria, pricing, loan features, turnaround time, security requirements and documentation requirements.
For example, a self-employed borrower may need a lender comfortable with variable income or alternative business records. A business seeking equipment finance may need a lender that understands the asset class. A borrower with past credit issues may need a lender with policies that consider the full context rather than only the credit score.
Consumer loans and business loans may be treated differently
Australian borrower protections can differ depending on whether the loan is for personal, domestic or household purposes, or for business and investment purposes. Some consumer credit activities are regulated under Australian credit laws and may require an Australian credit licence or authorised credit representative status. Business lending can involve different obligations, documents and risk considerations.
Borrowers should understand their rights, the role of credit licensing, disclosure documents, hardship options and complaint pathways. For more detail, read this guide to borrower rights and responsible lending protections in Australia.
If you are unsure about legal, tax or financial implications, consider seeking qualified professional advice. A broker can explain finance options, but that does not replace independent legal, tax or financial advice tailored to your circumstances.
Questions to ask a broker before proceeding
Before you agree to use a broker or accept a loan offer, consider asking:
- Are you a licensed credit provider, credit representative, broker or referral partner?
- Which company will handle my application?
- Which lenders are on your panel?
- How many lenders have you considered for my scenario?
- Why are you suggesting this lender or product?
- How are you paid, and will I pay any broker or application fees?
- Will applying affect my credit report?
- What documents will the lender need?
- What are the total costs, not just the repayment amount?
- What happens if I repay early, miss repayments or want to refinance?
- Who can I contact if I have a complaint?
Information and documents a broker may request
The documents requested will depend on the loan type, borrower profile and lender policy. Common examples include:
- identification documents;
- proof of income, such as payslips or business financials;
- bank statements;
- details of existing debts and regular expenses;
- credit report information or permission for credit checks;
- asset details for secured loans;
- business registration details, tax records or BAS information for business borrowers; and
- quotes or invoices for vehicles, equipment or machinery finance.
Only provide information through secure and legitimate channels. Be cautious if you are pressured to provide passwords, pay unusual upfront fees, exaggerate your income or sign blank documents.
Benefits of using a loan broker
A broker may help by narrowing down options, explaining lender requirements and preparing an application more efficiently. This can be useful if your circumstances are more complex, such as being self-employed, running a small business, seeking asset finance or having a credit history that needs context.
A broker may also help you understand trade-offs between interest rates, fees, loan terms, security, flexibility and approval conditions. However, the broker’s value depends on their panel, experience, transparency and how carefully they assess your needs.
Risks and limitations to keep in mind
Using a broker does not remove the need to make your own checks. Potential limitations include:
- the broker may not compare every lender in the market;
- commission structures may influence which products are recommended;
- some brokers may charge fees even if you do not proceed;
- submitting multiple applications may affect your credit report;
- loan approval and pricing remain subject to lender assessment; and
- business finance may involve guarantees, security or obligations that need careful review.
If something feels unclear, slow down and ask for written explanations. A trustworthy process should give you time to understand the proposed loan before signing.
Red flags when dealing with brokers or loan intermediaries
Be cautious if a broker or intermediary:
- promises approval before assessing your details;
- pressures you to act immediately without reviewing documents;
- asks you to provide false or incomplete information;
- refuses to explain fees, commissions or lender choice;
- does not identify the company or licence arrangement they operate under;
- asks for sensitive information through insecure channels; or
- discourages you from reading the loan contract.
A broker should help you make a more informed decision, not rush you into a product you do not understand.
How to prepare before speaking with a broker
You can make the conversation more productive by preparing in advance. Start by clarifying:
- how much you want to borrow and why;
- what repayment amount may be manageable within your budget;
- whether the loan is personal, business or asset-related;
- your current income, expenses and debts;
- your credit history and any issues that may need explanation;
- which documents you can provide quickly; and
- what features matter to you, such as repayment flexibility or early payout options.
Preparation does not guarantee approval, but it can help the broker and lender assess your situation more clearly.
Key takeaway
A loan broker in Australia can act as a useful guide between borrowers and lenders, especially where the borrower needs help understanding lender criteria, documentation or finance structures. The important point is to understand the broker’s role, how they are paid, which lenders they can access and what responsibilities remain with you as the borrower.
Before proceeding, ask clear questions, read all documents carefully and compare the total cost and conditions of any loan offer. A broker can support the process, but the right finance decision depends on your circumstances, the lender’s assessment and your ability to manage repayments over time.